Suggested: business owner reviewing a balance sheet and asset/liability breakdown.
 –>
Accounting Foundation
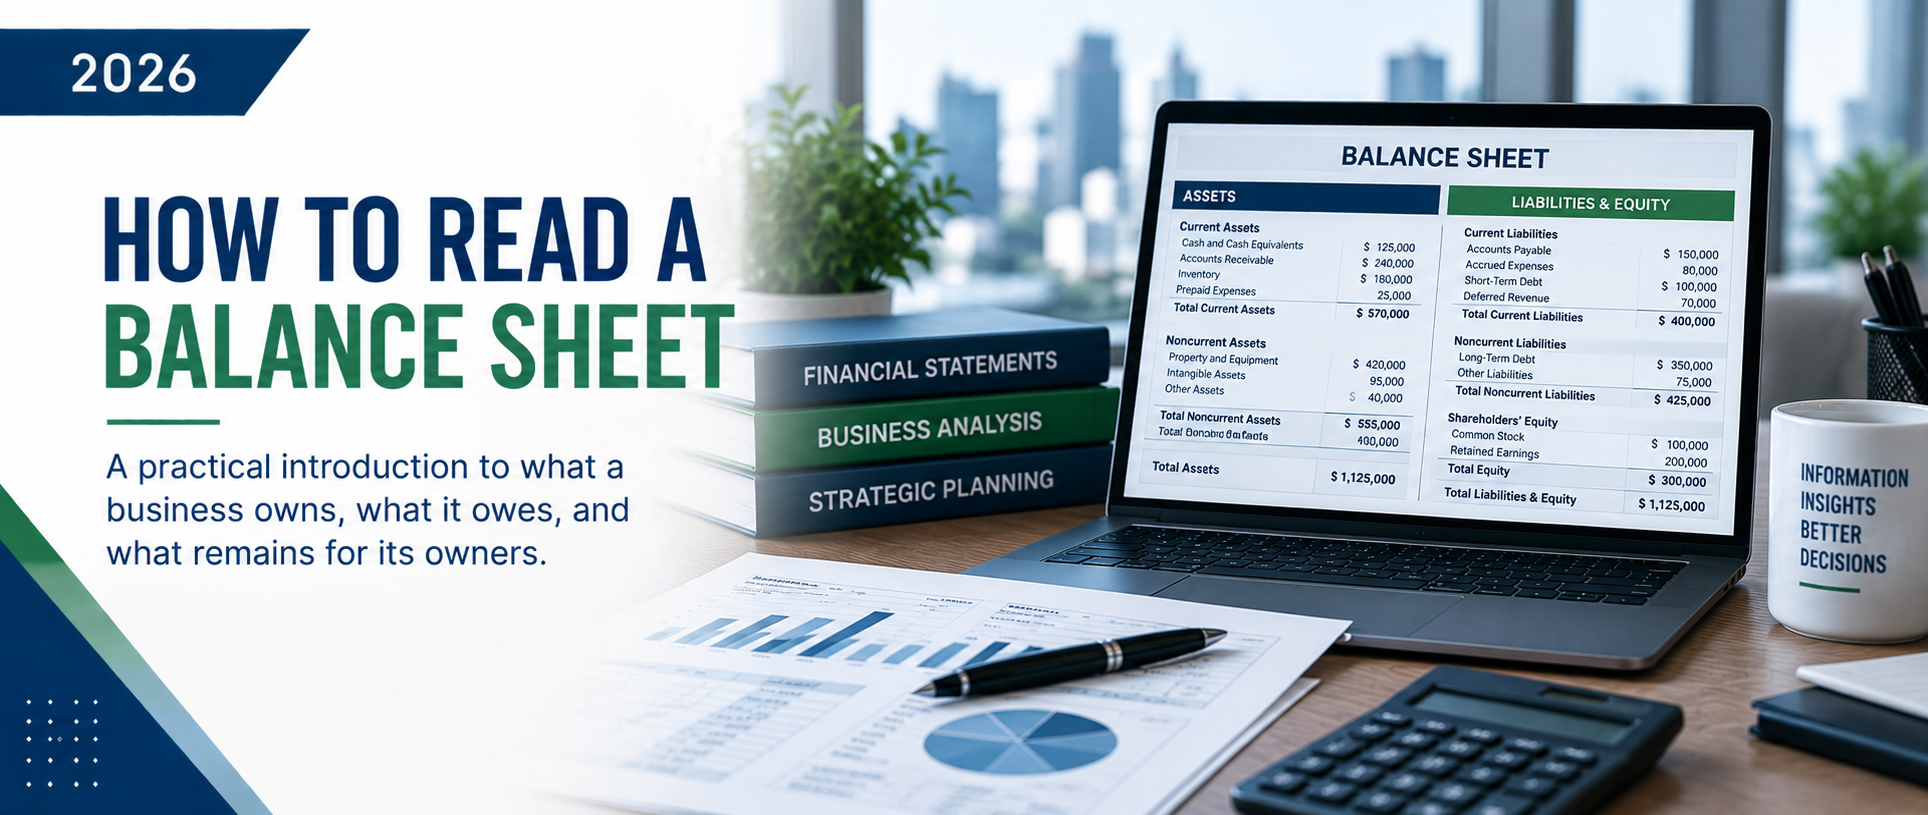
How to Read a Balance Sheet
A practical introduction to what a business owns, what it owes, and what remains for its owners.
A balance sheet should do more than balance. It should show whether the business has enough liquidity, manageable debt, supportable balances, and healthy owner equity.
1. Definition
A balance sheet is a snapshot of financial position at a specific date. It shows what the business owns, owes, and what remains for owners.
Assets = Liabilities + Equity
| Section | Basic Meaning | Common Examples |
|---|---|---|
| Assets | Resources the business owns or controls | Cash, receivables, inventory, equipment |
| Liabilities | Amounts the business owes to others | Payables, accrued expenses, taxes, loans |
| Equity | The owners’ residual interest after liabilities | Contributions, retained earnings, distributions |
The equation must always balance, but a balanced statement can still contain incorrect or unsupported accounts.
2. Why It Matters
A balance sheet helps management assess financial readiness and reporting quality.
- Liquidity: Can the company meet payroll, vendor, tax, and debt obligations?
- Working capital: Is too much cash tied up in receivables or inventory?
- Financial risk: Are debt, overdue payables, or negative equity becoming a concern?
- Reliability: Are major balances reconciled, supported, and reasonable?
3. How It Works
Step 1: Confirm the Date and the Equation
Confirm the reporting date and that Assets = Liabilities + Equity. Then compare major balances with the prior period. Balancing proves mathematical completeness—not account accuracy.
Step 2: Review the Quality of Assets
Focus on the quality and liquidity of assets. Cash should reconcile; receivables should be collectible; inventory should be moving; and long-term assets should be supported by records.
Step 3: Understand What the Business Owes
Review accounts payable, accrued expenses, taxes, payroll liabilities, and debt. Understand not only the total owed, but also due dates, interest rates, and lender requirements.
Step 4: Read Equity Correctly
Equity generally increases with contributions and retained profit and decreases with losses and distributions. Contributions are not revenue, and distributions are not operating expenses.
Step 5: Compare Trends and Basic Measures
Compare periods and investigate material changes. For example, cash falling while profit rises may signal slower collections, inventory purchases, debt repayment, or capital spending.
- Working capital = Current assets – Current liabilities
- Current ratio = Current assets / Current liabilities
No single ratio is “good” for every company. Consider industry, seasonality, payment terms, financing, and asset quality.
4. Simple Example
Assume the following simplified year-end balances:
| Category | Amount | What It Includes |
|---|---|---|
| Current assets | $700,000 | $200,000 cash, $300,000 receivables, $200,000 inventory |
| Long-term assets | $300,000 | Equipment and other long-term resources |
| Current liabilities | $500,000 | Payables, accruals, taxes, and current debt |
| Long-term liabilities | $200,000 | Debt due after the next year |
| Equity | $300,000 | Owner capital and accumulated results |
The statement balances at $1,000,000 of assets = $700,000 of liabilities + $300,000 of equity. Working capital is $200,000 and the current ratio is 1.4.
But liquidity needs a closer look: $500,000 of current assets is tied up in receivables and inventory. Management should review collection timing and inventory turnover before concluding liquidity is strong.
5. Common Mistakes
- Looking only at cash: Upcoming payroll, taxes, payables, and debt may materially reduce available cash.
- Treating all current assets as equally liquid: Receivables and inventory may not convert to cash quickly.
- Assuming large AR or inventory is positive: Old receivables and slow-moving inventory can signal risk.
- Reviewing debt only by total balance: Also check due dates, interest, covenants, and current maturities.
- Accepting unsupported accounts because the statement balances: Old “other,” suspense, or unreconciled balances still require support.
- Ignoring trends: One period alone may hide deterioration or unusual changes.
- Misclassifying owner activity: Contributions are not revenue; distributions are not operating expenses.
Quick Answers
- Market value? Usually not. Balance-sheet amounts follow accounting measurement rules and may differ from business value.
- Can a profitable business have a weak balance sheet? Yes. Profit can coexist with low cash, slow collections, excess inventory, heavy debt, or overdue obligations.
- Why might it not balance? Common causes include incomplete postings, mapping errors, import issues, or the wrong reporting date/entity.
6. Practical Checklist: What’s Next
Work through these items when reviewing the balance sheet.
0 of 7 complete
PNJ Perspective
A useful balance sheet is not just mathematically correct—it should be reconciled, supported, and easy for management to interpret. PNJ helps businesses strengthen balance-sheet reconciliations, month-end close, working-capital visibility, and management reporting.
Technical Reference Points
- SEC: Beginners’ Guide to Financial Statements
- FASB: Concepts Statement No. 8—Elements of Financial Statements
Disclaimer
This article provides general educational information and is not accounting, tax, legal, or investment advice. Financial-statement presentation and interpretation depend on the company’s accounting framework, industry, financing arrangements, and facts. Consult qualified advisers before acting.