Suggested: business owner organizing records in response to an IRS audit notice.
 –>
Tax Compliance Foundation
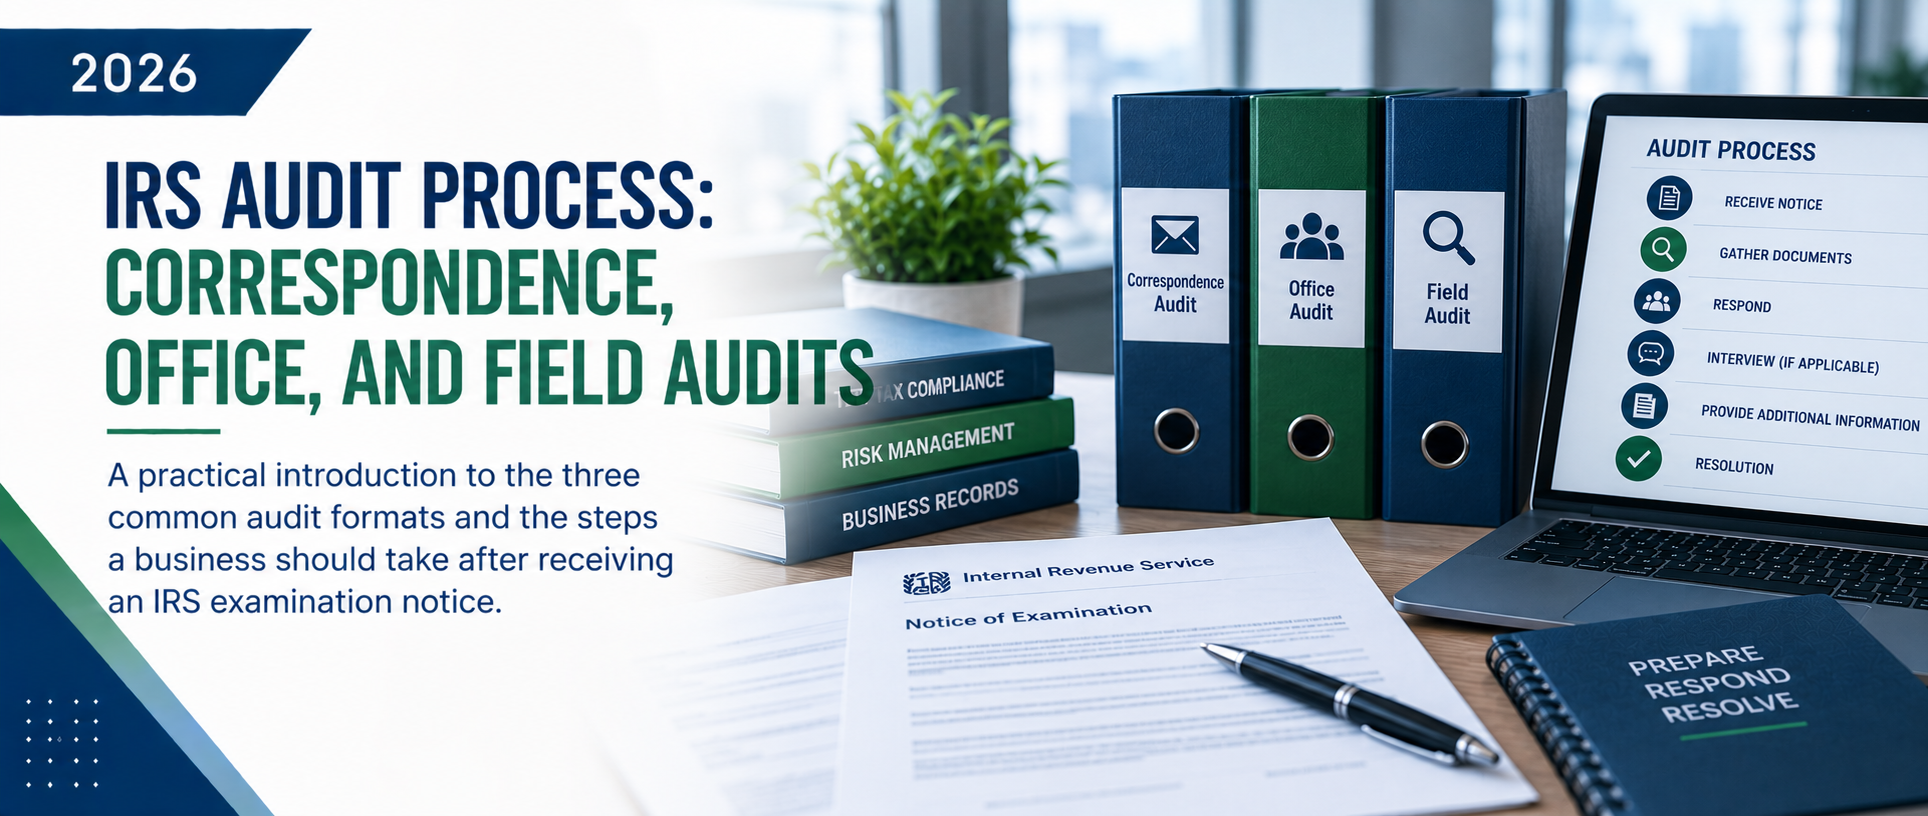
IRS Audit Process: Correspondence, Office, and Field Audits
A practical introduction to the three common audit formats and the steps a business should take after receiving an IRS examination notice.
An IRS audit notice does not automatically mean wrongdoing. First identify the audit type, issues, and deadline, then respond with organized records tied to the filed return.
1. Definition
An IRS audit, or examination, reviews a tax return and supporting records to determine whether income, deductions, credits, and tax were reported correctly. The result may be no change, an agreed change, or a disputed change.
Business audits are commonly conducted as correspondence, office, or field audits. The format determines how the review occurs—not the final outcome.
| Audit Type | How It Occurs | Typical Scope |
|---|---|---|
| Correspondence | Documents are exchanged by mail or an approved IRS submission method. | One or a few return items, such as income matching or support for a deduction. |
| Office | The taxpayer or representative meets with an IRS examiner at an IRS office or designated location. | Selected issues requiring records and an interview. |
| Field | A revenue agent examines records at the business, a representative’s office, or another agreed location. | Broader or more complex business issues, sometimes involving multiple returns or periods. |
2. Why It Matters
Each audit type requires a different response: focused written support for correspondence audits, meeting preparation for office audits, and controlled document management for field audits.
Deadlines are critical. Missing a response can lead to disallowed deductions, additional tax or penalties, or loss of procedural rights. Always follow the actual IRS notice for the required action and date.
- Accuracy: Tie each requested amount to the return, books, and supporting transaction.
- Consistency: Use one designated person to coordinate IRS communications.
- Rights: Taxpayers may explain their position, disagree with proposed changes, and use an authorized representative.
3. How It Works
The Audit Begins with Written Notice
Verify the written notice, calendar the response date, and retrieve the exact return, tax period, workpapers, and requested records before responding.
Correspondence Audit: Build a Focused Written Response
Answer each request in order. Send organized copies—not originals unless specifically requested, include a short explanation, label the support, and retain a complete copy plus proof of submission.
Office Audit: Prepare the Records and the Meeting
Reconcile requested amounts to the return, organize the support, and prepare clear, accurate explanations before the meeting. If an answer is unknown, verify it rather than guess.
Field Audit: Establish a Controlled Process
Field audits can cover general ledgers, bank records, payroll, fixed assets, contracts, owner transactions, and related returns. Assign one point of contact, track every request and deadline, review each production before submission, and document meetings and calls.
Respond to the issues actually under examination. Do not send unrelated records, but do not omit information needed to answer the IRS request accurately and completely.
Review the Result
The IRS may accept the return or propose changes. Before agreeing, review the adjustment, tax, interest, penalties, and available rights. Depending on the notice and case, Appeals or court review may be available.
Taxpayers may represent themselves or authorize an attorney, CPA, or enrolled agent using Form 2848. Representation is especially useful for in-person audits, complex issues, incomplete records, multiple periods, or material proposed adjustments.
4. Simple Example
A business receives a correspondence-audit request for support of $28,000 of repair expenses. A strong response would:
- Confirm scope: Verify the tax year, expense category, requested documents, and deadline.
- Reconcile the amount: Tie the $28,000 from the return to the tax workpaper and general ledger.
- Organize support: Index invoices, payment evidence, and descriptions of the work.
- Explain and retain proof: Briefly connect the records to the repair treatment and keep proof of submission.
The IRS may accept the support, request more information, or propose capitalization of some costs. Review any proposal item by item and respond by the stated deadline.
5. Common Mistakes
- Ignoring the first notice: Do not assume another copy went to the preparer.
- Sending support before reconciling it: Tie the requested amount to the filed return first.
- Sending original records unnecessarily: Use clear copies unless the IRS specifically requests originals.
- Using multiple communicators: Centralize examiner contact through one designated person.
- Guessing in an interview: Verify facts and follow up rather than give inconsistent answers.
- Missing procedural deadlines: Protect response, Appeals, and court deadlines even if records are still being gathered.
6. Practical Checklist: What’s Next
Work through these items as soon as an examination notice arrives.
0 of 6 complete
PNJ Perspective
An IRS examination is easier to manage when tax returns, accounting records, supporting documents, deadlines, and communications are controlled in one process. PNJ helps businesses organize the response, reconcile requested amounts, and coordinate with authorized tax representatives when appropriate.
Sources and Professional Notes
- IRS: Audits
- IRS Publication 3498: The Examination Process
- IRS Publication 556: Examination and Appeal Rights
- IRS: Form 2848, Power of Attorney
Disclaimer
This article provides general educational information and is not tax or legal advice. IRS procedures and rights depend on the notice, taxpayer, issue, tax period, and facts. Review the actual correspondence and consult a qualified adviser about a specific examination.