Suggested: business owner reviewing a U.S. map of state filing obligations and remote employee locations.
 –>
Tax Compliance Foundation
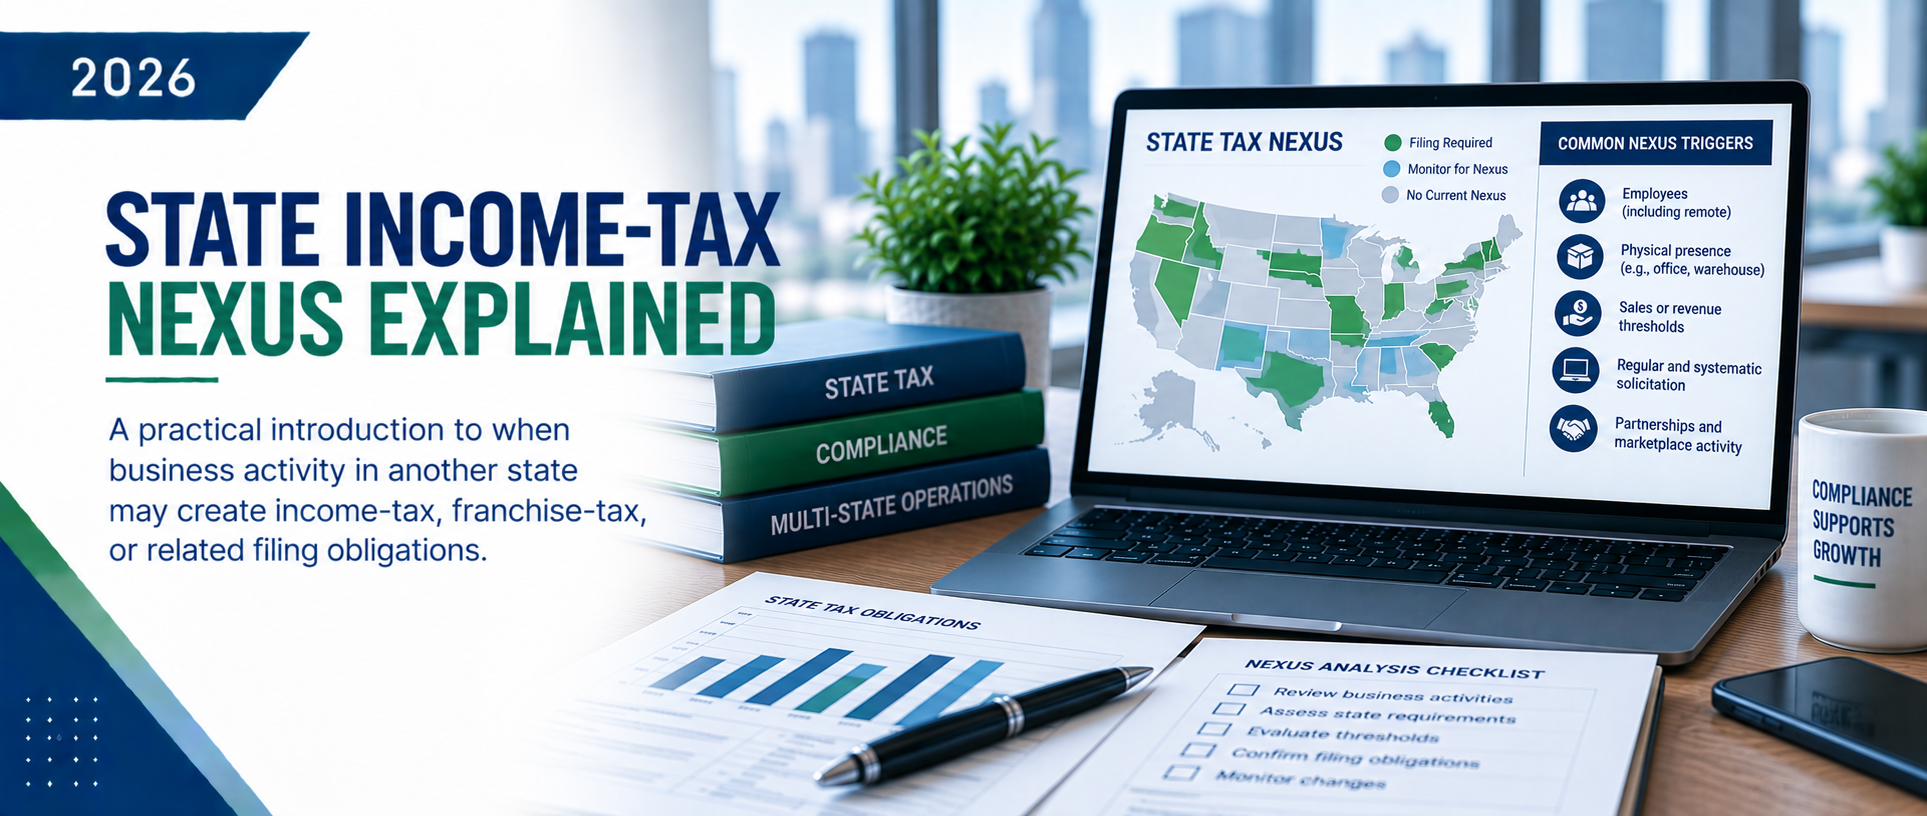
State Income-Tax Nexus Explained
A practical introduction to when business activity in another state may create income-tax, franchise-tax, or related filing obligations.
State income-tax nexus can arise when a business has sufficient connection with a state—even without an office there. Employees, property, inventory, in-state services, or economic activity may trigger filing obligations. Review nexus state by state and tax by tax.
1. Definition
State income-tax nexus is the connection that allows a state to require an income-tax or similar business-tax return. The connection may come from people, property, transactions, or economic activity.
Nexus is tax-specific. Sales-tax nexus, payroll nexus, and income-tax nexus answer different questions. One review does not automatically satisfy the others.
2. Why It Matters
- Multistate filing: A business may owe returns, registrations, estimated payments, minimum taxes, or fees outside its formation or home state.
- Pass-through entities still have exposure: The entity or its nonresident owners may face state tax, withholding, or filing requirements.
- Historical exposure can grow: Unfiled years may remain open and accumulate tax, penalties, and interest—often discovered during audits, financing, acquisitions, or due diligence.
3. How It Works
There is no single national income-tax nexus threshold. Each state sets its own filing rules, thresholds, tax types, and exceptions. A sound review begins with the business’s actual multistate footprint.
Physical Presence
People and property remain common triggers. Nexus may arise from an office, remote employee, inventory, equipment, or personnel performing services in the state.
Remote work deserves special attention. An employee moving or being hired in another state can affect income tax, payroll registration, withholding, unemployment insurance, and other filings even when the company has no customer-facing location there.
Economic Presence
Some states impose nexus based on economic activity without physical presence. Sales, receipts, property, or payroll thresholds may apply, and measurement periods, sourcing rules, and entity coverage vary by state.
| Potential Trigger | Business Activity | Why It Requires Review |
|---|---|---|
| People | Remote employee, owner, contractor, or traveling staff | May create physical presence and related payroll obligations |
| Property | Office, equipment, vehicles, or inventory | Property in the state can create a direct connection |
| Services | Installation, consulting, repair, training, or support | In-state performance may exceed protected solicitation |
| Economic activity | Significant sales or receipts from customers in the state | A state may apply an economic or factor-presence standard |
P.L. 86-272: A Narrow Federal Protection
P.L. 86-272 may protect certain out-of-state businesses from a state net income tax when in-state activity is limited to protected solicitation of orders for tangible personal property and statutory conditions are met.
The protection is narrow. It generally does not protect services, intangible products, sales tax, payroll tax, franchise tax, gross-receipts tax, installation, repair, consulting, customer support, inventory, or certain internet activities.
What Happens After Nexus Exists?
Nexus answers whether a state may require filing—not how much tax is due. After nexus is identified, determine the return, filing period, tax base, minimum tax, payment requirements, and apportionment.
State taxable income may differ from federal taxable income. The sequence is:
- Determine nexus for each relevant state.
- Identify the tax and return that apply.
- Determine the state share using apportionment and sourcing rules.
- Confirm payment and owner-level requirements.
4. Simple Example
Assume a Texas software consulting company has no office outside Texas, but hires a remote employee in Colorado, develops meaningful sales in California, and sends staff to customer sites for implementation and training.
- Colorado: The remote employee creates a clear reason to review corporate income-tax and payroll obligations.
- California: Compare customer receipts with current economic-nexus thresholds and sourcing rules.
- Other customer states: On-site implementation or training may create physical-presence nexus.
- Texas: Continue home-state compliance while adding any required out-of-state filings.
The lesson is not to register everywhere. Identify states with meaningful activity, apply each state’s rules, document the conclusion, and act before multiple unfiled years accumulate.
5. Common Mistakes and Quick Answers
Common Mistakes
- Filing only where the business was formed: Physical or economic activity can create obligations elsewhere.
- Reviewing sales tax only: Income-tax and payroll nexus must be evaluated separately.
- Ignoring employee moves: Accounting, Payroll, and Tax should be notified before or when an employee changes work state.
- Using one state’s threshold everywhere: Each state has its own nexus and sourcing rules.
- Treating P.L. 86-272 as a blanket exemption: Its protection is narrow and tax-specific.
- Registering prospectively without reviewing history: Measure possible historical exposure and remediation options first.
Quick Answers
- Does one sale always create income-tax nexus? Not necessarily. The answer depends on the state, tax type, activity, sourcing rules, thresholds, and available protection.
- If a marketplace collects sales tax, is income-tax nexus covered? No. Marketplace-facilitator rules generally address sales-tax collection only. Income-tax or business-tax nexus must be reviewed separately.
6. Practical Checklist: What’s Next
Work through these items to build or refresh a state nexus review.
0 of 7 complete
PNJ Perspective
State nexus is best managed as an ongoing business process—not a year-end tax check. PNJ helps businesses connect employee locations, property, customer activity, P.L. 86-272, apportionment, historical exposure, and filing obligations so multistate compliance stays aligned with how the business actually operates.
Technical Reference Points
- Multistate Tax Commission: P.L. 86-272 Statement of Information
- California Franchise Tax Board: Doing Business in California
- Colorado Department of Revenue: Corporate Income Tax Guide
Disclaimer
This article provides general educational information and is not tax, accounting, or legal advice. State nexus, sourcing, apportionment, P.L. 86-272, filing thresholds, entity-level taxes, and remediation programs vary by jurisdiction and facts. Current state guidance should be confirmed before registering, filing, or changing a tax position.