Suggested: Small finance team at a table with a printed year-end checklist, ledgers and a calendar showing late November.
 –>
PNJ Group | Accounting Insight
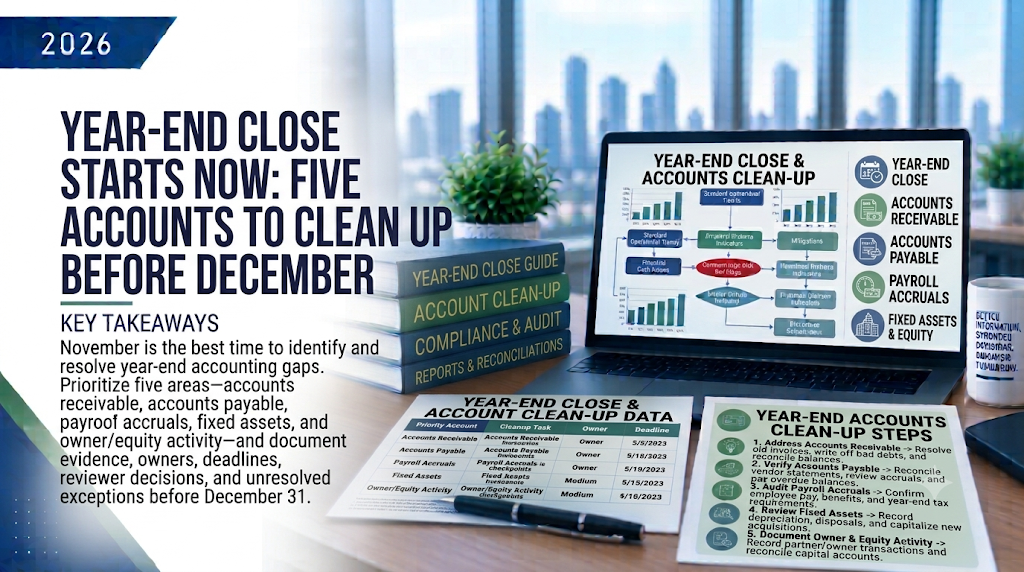
Year-End Close Starts Now: Five Accounts to Clean Up Before December
November is the best time to identify and resolve year-end accounting gaps. Prioritize five areas—accounts receivable, accounts payable, payroll accruals, fixed assets, and owner/equity activity—and document evidence, owners, deadlines, reviewer decisions, and unresolved exceptions before December 31.
1. Checklist Purpose, Scope, and Timing
This pre-close checklist is for U.S. small-business owners, bookkeepers, controllers, and finance teams preparing 2026 calendar-year financial statements. Apply it separately to each legal entity; adapt it for fiscal-year businesses and the entity’s accounting method.
- Target timeline: Perform initial reviews in November 2026; resolve critical items by December 31, 2026; finalize year-end cutoffs during the January close.
- Objective: Identify missing balances, unsupported transactions, and reporting risks while corrective action and documentation are still possible.
2. Prioritized Tasks Grouped by Area
Use these action-oriented checks in priority order. Mark each item Yes, No, or N/A; a “No” requires an owner and follow-up date.
Priority 1 — Accounts Receivable (AR)
0 of 2 complete
Priority 2 — Accounts Payable (AP)
0 of 2 complete
Priority 3 — Payroll and Bonuses
0 of 2 complete
Priority 4 — Fixed Assets
0 of 2 complete
Priority 5 — Equity and Owner Activity
0 of 2 complete
3. Source Documents, Owner, and Deadline
| Area | Evidence / source documents | Primary owner | Target |
|---|---|---|---|
| AR | AR aging, customer statements, credit memos, collection support | AR / Accounting | Nov. 20 |
| AP | AP aging, vendor statements, POs, open invoices, W-9 files | AP / Accounting | Nov. 20 |
| Payroll | Payroll register, PTO report, bonus approvals, GL detail | Payroll / Controller | Nov. 30 |
| Fixed assets | Asset register, invoices, disposal documents, in-service support | Accounting / Controller | Nov. 30 |
| Owner / equity | GL detail, loan agreements, distribution approvals, bank support | Controller / Owner | Dec. 15 |
Illustrative internal deadlines only; adjust for the entity’s closing calendar and filing requirements.
4. Verification and Escalation Indicators
- Verification: Each account agrees to the general ledger; key reconciling items have documented explanations; proposed adjustments are posted or approved; supporting schedules are retained.
- Red flags: Old receivables without follow-up, unrecorded supplier invoices, unexplained payroll differences, missing asset disposal records, or owner payments without clear classification.
- Escalate to the Controller / tax adviser when: a material unreconciled difference remains, the tax treatment is uncertain, a debt or related-party transaction is undocumented, or a deadline cannot be met.
5. Final Sign-Off and Readiness Test
An area is marked “Ready” only when its reconciliation is complete, required documentation is attached, adjustments are recorded or formally approved, and no material unexplained exceptions remain.
- Preparer sign-off: Confirms the balances, check items, and evidence are complete.
- Reviewer sign-off: Controller or designated reviewer approves adjustments and confirms any unresolved items are assessed for financial statement and tax impact.
- Exceptions: Open items must have an assigned owner, amount or exposure, resolution date, and escalation decision. Do not mark the overall close ready when a material unresolved exception remains.
6. Reusable Year-End Close Workpaper
Use the same compact tracker for all five account areas and roll outstanding items forward into the final December close:
| Area / action | Status | Evidence link | Owner / due date | Reviewer / exception |
|---|---|---|---|---|
| AR aging: >90-day balances | Yes / No / N/A | Aging + follow-up | AR lead / 11-20 | Reviewer / notes |
| AP completeness: unbilled items | Yes / No / N/A | Statements + accruals | AP lead / 11-20 | Reviewer / notes |
| Payroll: wages, PTO, bonuses | Yes / No / N/A | Reports + approvals | Payroll / 11-30 | Reviewer / notes |
| Fixed assets: rollforward | Yes / No / N/A | Register + invoices | Accountant / 11-30 | Reviewer / notes |
| Owner / equity: transactions | Yes / No / N/A | GL + agreements | Controller / 12-15 | Reviewer / notes |
A November review reduces surprises, but it does not replace December cutoff testing, final reconciliations, year-end tax analysis, or January information-return preparation.
How PNJ Group Can Help
PNJ Group supports businesses with account reconciliations, payroll and fixed-asset reviews, owner-transaction classification, closing workpapers, and controller-level sign-off.
Reference note
Based on the supplied November 2026 PNJ year-end article. Tax treatment of bad debts, bonus accruals, depreciation, information returns, and shareholder benefits depends on current law and entity-specific facts.