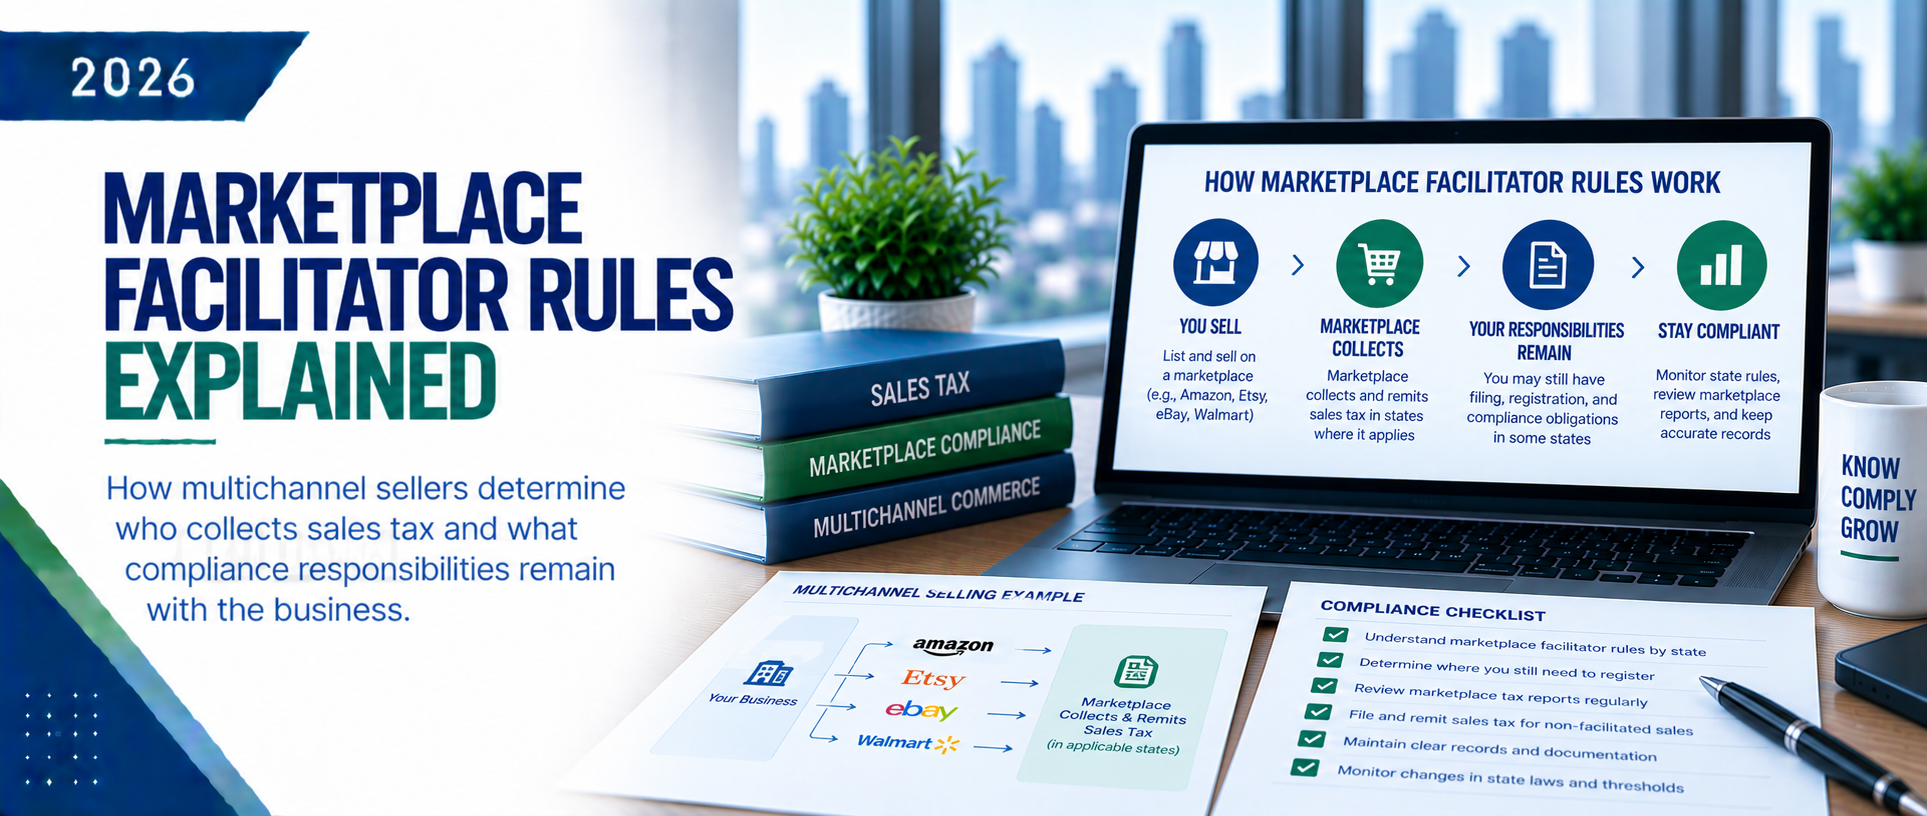
Suggested: multichannel seller reviewing marketplace and direct-sales tax reports side by side.
 –>
Tax Compliance Practice Guide | Intermediate
Marketplace Facilitator Rules Explained
How multichannel sellers determine who collects sales tax and what compliance responsibilities remain with the business.
Marketplace facilitator relief applies only to covered sales and states. The seller still must confirm platform qualification, nexus, direct-sale obligations, product taxability, exemptions, filing duties, and reconciliation.
1. Definition
A marketplace facilitator generally operates or controls a marketplace and performs transaction-related activities such as payment processing or collection. Exact definitions vary by state; a website, payment processor, ad platform, or fulfillment provider does not automatically qualify.
A marketplace seller sells through the facilitator. When state law applies and the facilitator assumes responsibility, it generally collects and remits tax on qualifying sales. Direct sales through the seller’s own website, invoices, store, or sales team remain the seller’s responsibility.
2. Why It Matters
- Collection relief is limited: Marketplace laws may shift collection responsibility, but the seller may still have permit, return, nexus, exemption, or reporting duties.
- Channel separation matters: Poor separation can cause duplicate remittance or undercollection. Marketplace inventory or fulfillment can also create other state-tax or registration questions.
3. How It Works
Confirm That the Platform Qualifies
Review the platform agreement, state definition, certification, covered states, products, and transaction types. Do not stop collecting tax based only on the platform name.
Retain facilitator certification, marketplace tax reports, settlement reports, and state-specific documentation with the tax files.
Separate Marketplace and Direct Sales
| Sales Channel | Who Usually Collects | Seller Responsibility |
|---|---|---|
| Qualified marketplace sale | Marketplace facilitator | Verify coverage; retain certification and transaction-level reports |
| Company website or app | Seller | Collect when nexus and taxability rules require it |
| Sales team or direct invoice | Seller | Determine sourcing, exemptions, and correct tax treatment |
| Wholesale or resale transaction | Marketplace or seller, depending on channel | Confirm who retains the resale or exemption certificate |
Maintain channel-level reporting by state for marketplace sales, direct sales, refunds, product taxability, tax collected, and exemptions. Also track a combined state-sales view for nexus monitoring because marketplace sales may count differently by state.
Determine the Sellers Remaining State Duties
Marketplace collection does not eliminate nexus. Employees, offices, inventory, contractors, fulfillment activity, or sales volume can still create state obligations. Registration and return relief varies by state.
Texas illustrates the distinction: a marketplace-only remote seller using a certified marketplace may receive permit relief, while an in-state seller may still need a permit and returns even if all sales are facilitated. Other states apply their own rules.
| Compliance Question | Marketplace Effect | Seller Review |
|---|---|---|
| Sales-tax collection | Facilitator may assume collection for covered sales | Confirm certification, states, products, and effective dates |
| Registration and returns | May provide limited relief in some states | Check physical presence, direct sales, and state filing instructions |
| Economic nexus | Marketplace sales may still enter the threshold | Track direct, marketplace, and combined state sales |
| Other state taxes | Usually not resolved by facilitator law | Review income, franchise, gross-receipts, property, and business filings |
Maintain Product and Exemption Controls
Product taxability still matters. Marketplace laws do not change whether the underlying product is taxable or exempt. Platforms may rely on seller-provided product codes, descriptions, shipping data, and exemption settings.
Confirm who collects and retains exemption certificates. Keep support for unusual classifications, update product codes when offerings change, and reconcile exempt transactions separately.
Reconcile Marketplace Activity and Tax
Reconcile gross orders, refunds, marketplace fees, tax, and net cash settlements. Marketplace tax reports should agree to return reporting and facilitator documentation; direct-channel tax should reconcile to sales-tax payable and remittances.
If the facilitator is legally responsible for the tax, the marketplace-collected amount generally is not the seller’s sales-tax payable. Do not record it as revenue or remit it again.
4. Simple Example
Assume a retailer has $30,000 of Texas marketplace sales and $20,000 of taxable direct website sales during the month.
| Channel | Gross Sales | Collector | Seller Action |
|---|---|---|---|
| Marketplace | $30,000 | Marketplace provider | Retain certification and reports; include activity as Texas instructions require |
| Direct website | $20,000 | Seller | Collect, report, and remit when the seller has Texas responsibility |
The channels are reported and reconciled separately. The seller should not remit marketplace-collected tax again, while direct taxable sales remain its responsibility. Total state activity still matters for nexus and other state-tax analysis.
5. Common Mistakes and Quick Answers
Common Mistakes
- Assuming every platform qualifies: Confirm facilitator status under each state’s law.
- Treating marketplace collection as full compliance relief: Permit, return, nexus, and reporting duties may remain.
- Ignoring direct sales or fulfillment inventory: Track each channel and physical presence separately.
- Excluding marketplace sales from nexus automatically: Check the applicable state threshold rule.
- Using unsupported product codes or missing certification: Maintain product and facilitator documentation.
- Remitting marketplace tax twice: Do not treat facilitator-collected tax as the seller’s payable when the facilitator is legally responsible.
Do Marketplace Sales Count Toward Economic Nexus?
Sometimes. Economic-nexus statutes differ. Track direct, marketplace, and combined state sales and exclude marketplace activity only after confirming the applicable rule.
Does Marketplace Collection Eliminate Other State Taxes?
No. Facilitator laws address sales-tax collection. Inventory, employees, registrations, or economic activity can still create income, franchise, gross-receipts, property, or business-filing obligations.
6. Practical Checklist: What’s Next
Work through these role-based items to manage marketplace and direct-channel compliance.
0 of 7 complete
PNJ Perspective
Marketplace facilitator rules should be managed by channel and state—not by assuming the platform handles everything. PNJ helps sellers connect facilitator certification, nexus, direct-sale responsibilities, product taxability, exemptions, filing calendars, and reconciliation so marketplace relief does not create hidden compliance gaps.
Technical Reference Points
- Texas Comptroller: Marketplace Providers and Marketplace Sellers
- California CDTFA: Marketplace Facilitator Act
- State Department of Revenue marketplace-facilitator guidance applicable to each filing jurisdiction
Disclaimer
This article provides general educational information and is not tax or legal advice. Marketplace definitions, facilitator liability, seller relief, nexus thresholds, registration and filing duties, product taxability, and documentation requirements vary by state and can change. Confirm the rules for each platform, channel, state, and period.