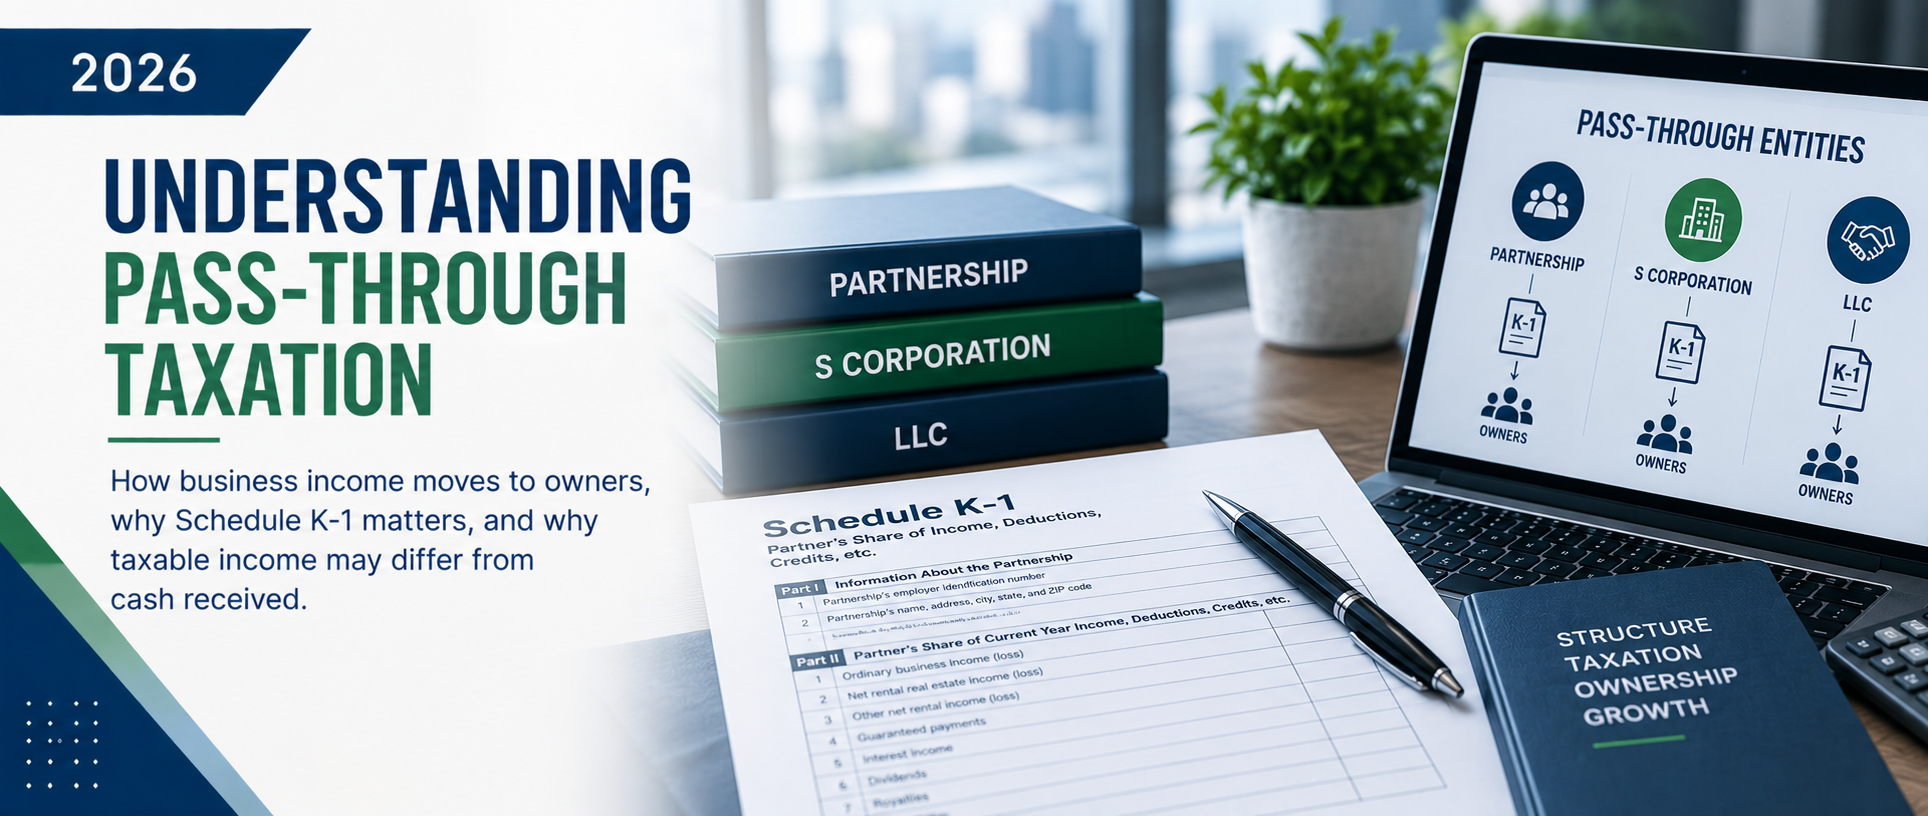
Suggested: business owner reviewing a Schedule K-1 and owner basis worksheet.
 –>
Tax Foundation
Understanding Pass-Through Taxation
How business income moves to owners, why Schedule K-1 matters, and why taxable income may differ from cash received.
Pass-through taxation does not eliminate tax. Business income generally flows to the owners, who may owe tax even when the cash stays in the business.
1. Definition
- How it works: Pass-through entities generally calculate tax items at the business level, while owners report their share on their own returns.
- Main forms: A disregarded single-member LLC, a partnership / LLC taxed as a partnership, and an S corporation. An LLC is a legal structure, so federal tax treatment depends on ownership and elections.
| Business Type | Federal Return | Owner Reporting | General Treatment |
|---|---|---|---|
| Single-member LLC | Usually reported with owner return | Schedule C, E, or F, as applicable | Activity is generally reported directly by the owner |
| Partnership / LLC taxed as partnership | Form 1065 | Schedule K-1 | Tax items generally pass to partners |
| S corporation | Form 1120-S | Schedule K-1 | Tax items generally pass to shareholders |
2. Why It Matters
- Avoids a second federal income-tax layer: Pass-through income is generally taxed to the owners rather than first at the entity and again on dividends.
- Tax can arise without cash: Owners may owe tax on allocated income even when distributions are smaller—or none are made.
- Cash planning matters: Estimated taxes and a tax-distribution policy can help owners fund tax while preserving cash for payroll, debt, inventory, and growth.
3. How It Works
Step 1: The Business Calculates Taxable Items
The business determines ordinary income and separately stated tax items. Taxable income may differ from book income.
Step 2: Items Are Allocated to the Owners
Partnerships generally allocate items under the partnership agreement and tax rules. S corporations generally allocate by ownership on a per-share, per-day basis. Ownership changes can affect the result.
Step 3: Schedule K-1 Connects the Returns
A partnership or S corporation issues Schedule K-1 showing each owner’s share of reportable items. K-1 income does not necessarily equal cash received.
Step 4: Owner Payments Follow Separate Rules
- S corporation shareholders: Working owners generally need reasonable W-2 compensation before non-wage distributions. Wages are subject to payroll tax; pass-through business income generally is not self-employment income.
- Partners: Partners generally are not W-2 employees of the partnership; service payments may be guaranteed payments or partnership allocations.
- Distributions: Cash distributions are separate from taxable allocations and may reduce owner basis.
Step 5: Basis and Other Limits Are Reviewed
Basis tracks an owner’s tax investment. It generally increases with contributions and allocated income and decreases with distributions and allocated losses. It can affect whether distributions are taxable and losses are deductible.
A K-1 loss is not automatically deductible. Basis, at-risk, passive-activity, and other owner-level limits may suspend the loss. Maintain annual basis records.
Federal pass-through treatment does not eliminate state entity taxes, franchise fees, nonresident withholding, composite filings, or owner filing obligations.
4. Simple Example
Assume an S corporation earns $300,000 and has three equal shareholders. Each is allocated $100,000 but receives only $40,000 in cash.
- Taxable allocation: Each shareholder generally reports $100,000 through Schedule K-1.
- Cash distribution: The $40,000 distribution is a separate cash event and generally reduces basis if sufficient basis exists.
- Cash retained: The remaining $60,000 stays in the company, but tax may still apply to the full $100,000 allocation.
This is commonly called “phantom income”: the income is taxable even though the cash remains in the business. A tax-distribution policy can reduce surprises.
5. Common Mistakes
- Assuming pass-through means tax-free: Owners generally owe tax on their allocated income.
- Equating distributions with taxable income: Cash paid and taxable income are separate calculations.
- Reading only K-1 ordinary income: Separately stated items can affect the owner’s return differently.
- Claiming losses without checking limits: Basis, at-risk, and passive-activity rules may restrict deductions.
- Using the wrong owner-payment method: S corporation wages and partnership payments follow different rules.
- Ignoring state and ownership changes: State filings, withholding, estimated taxes, and ownership changes can materially affect reporting.
6. Practical Checklist: What’s Next
Work through these items to keep pass-through reporting and owner obligations aligned.
0 of 8 complete
PNJ Perspective
Pass-through taxation works best when entity reporting, owner basis, compensation, distributions, and tax planning are managed together. PNJ helps businesses coordinate these areas so taxable income, cash distributions, and owner obligations stay aligned.
Technical Reference Points
- IRS: Partnerships
- IRS: S Corporations
- IRS: Single-Member Limited Liability Companies
- IRS: S Corporation Stock and Debt Basis
- IRS: Qualified Business Income Deduction
Disclaimer
This article provides general educational information and is not tax or legal advice. Pass-through reporting, basis, loss limitations, compensation, distributions, and state obligations depend on the entity and each owner’s facts. Consult qualified tax and legal advisers before acting.